

Gravy: Homebuying for renters
Gravy Technologies
- 4.5
- 49.00 Reviews
- 10.00K
- Downloads
- Free
- Price
Screenshots
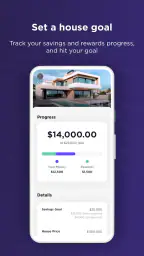
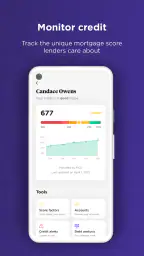
Gravy: Homebuying for renters Pros and Cons
Pros
- Personalized home listings can match renters’ budgets and preferences.
- Useful guidance helps first-time buyers understand the purchasing process.
- Mortgage and affordability tools can clarify realistic price ranges.
- Saved searches make it easy to track interesting properties over time.
- A renter-focused approach makes the transition to ownership less intimidating.
Cons
- Availability and features may vary significantly by location.
- Some listings may redirect you to external agents or partner services.
- Property data can become outdated as homes sell or prices change.
- Buying guidance cannot replace advice from a lender or real estate professional.
- Users may receive marketing messages after requesting information.
 Analysis by All-app
Buying a first home can feel like trying to solve several problems at once: saving enough money, understanding unfamiliar terms, watching your credit, and deciding whether renting for another year is sensible. Gravy: Homebuying for renters approaches that situation as a finance app built around the homebuying journey. I found it most useful when I treated it as a planning companion rather than a replacement for a lender, mortgage broker, or carefully maintained household budget.
The app is free to install, with optional in-app purchases ranging from $4.99 to $59.99 per item. It is developed by Gravy Technologies and is aimed at everyone, which makes the presentation approachable even if the subject itself can be intimidating. Its store summary describes it as a super app for first-time homebuyers, but the important question is how well that broad idea works in everyday use. My answer is that it can give renters a more focused way to organize their next steps, provided they are comfortable checking details and making the final financial decisions themselves.
Building a repeatable homebuying routine
The best way to use Gravy is to begin with a simple baseline workflow. I would not open it only when a property catches my eye, because that turns the app into a source of occasional excitement instead of a planning tool. A better habit is to use it during a regular money check-in, alongside rent, savings, debts, and the amount I could realistically put toward a future home.
That routine matters because a home purchase is not just a question of whether I can imagine the monthly mortgage payment. I also need to think about the upfront money, moving costs, repairs, insurance, taxes, and the possibility that my income or living costs may change. Gravy is most helpful when I use its homebuying focus to keep those questions in view rather than letting a single attractive listing define my budget.
For a renter who has never gone through the process, the app can make the journey feel less abstract. Instead of treating “buy a home” as one enormous target, I can break it into smaller decisions: how much to save, what kind of property fits my situation, what information I need before speaking with a professional, and which assumptions need checking. That is a more useful starting point than jumping straight into mortgage calculators or property searches without knowing what I can actually sustain.
A realistic example would be a renter who receives a regular paycheck, has some savings, and wants to buy within the next few years. I would use Gravy during a monthly review to compare progress with the original plan, then write down any change in income, debt, or expected moving costs. If the plan starts looking tight, the right response is not to stretch immediately for a more expensive home. The app is better used as a prompt to revisit the target and timeline.
That workflow also answers an important practical question: can this app replace a full personal finance system? In my experience, it should not. A general budgeting app or spreadsheet is usually better for detailed categories, account reconciliation, and a complete view of household cash flow. Gravy’s value comes from keeping the homebuying goal central. I would pair it with a broader budget rather than asking it to become one.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
What to check before trusting your plan
Settings and account choices deserve attention before I rely on any projection or reminder. I would first review the information I entered for income, savings, debts, and housing goals, because a neat result built on an optimistic estimate is still an optimistic result. If my income varies, I would use a conservative figure rather than my best month. If I share expenses with someone else, I would decide clearly which costs are joint and which are personal.
I would also check notification preferences. A homebuying app can become irritating if it sends more prompts than I can use, but turning everything off may remove the gentle reminders that make a savings habit work. My preference is to keep only notifications that support a specific action, such as reviewing progress or revisiting a target, and silence anything that encourages me to browse when I am not ready to make a decision.
Privacy is another reason to be deliberate. Finance apps deserve the same caution as banking tools, even when they are not handling transactions. I would avoid entering information I do not need for the planning task, use a strong device lock, and review permissions and account settings after installation. The app’s friendly tone should not encourage me to share more personal financial detail than necessary.
It is also worth checking the version shown on the device. The current version is 2.4.73, and the app requires Android 8.0 or later. That makes compatibility straightforward for many Android users, but anyone using an older phone should confirm the operating system before building a routine around it. The app has been available since August 13, 2021, so it is not a brand-new experiment, although that alone should never be treated as proof that every feature suits every buyer.
One setting-related habit I found valuable is separating “comfortable” from “possible.” If an app lets me consider a target home or savings goal, I should create my own second test: would the payment still feel manageable after a repair, a higher utility bill, or a temporary reduction in income? This is where a basic spreadsheet or notes app complements Gravy. The finance app can keep the goal visible, while my own stress test keeps enthusiasm under control.
Faster patterns for people who already know their numbers
Experienced users can move through the app more efficiently by preparing their information before opening it. I would keep a short note with current savings, recurring debts, monthly rent, and a conservative amount available for housing. That avoids repeatedly guessing and makes each review comparable. It also exposes changes: if the plan looks different, I can see whether the cause was new debt, lower savings, or an unrealistic earlier assumption.
Another useful pattern is to review progress after a real financial event rather than only on a fixed calendar date. A pay increase, a change in rent, a paid-off loan, or an unexpected expense can all alter the homebuying picture. Updating the plan at those moments is more informative than opening the app out of habit and leaving every figure unchanged.
I would also use a two-pass method. In the first pass, I would look only at the broad direction: am I saving consistently, and is the target still reasonable? In the second, I would inspect the details that could derail the plan, such as debt payments or cash needed for moving and repairs. This prevents me from confusing a positive savings trend with readiness to buy.
For renters comparing buying with staying put, the useful shortcut is to keep the comparison grounded in total housing cost. Rent is easy to see because it arrives as a familiar monthly bill. Ownership brings less obvious expenses and responsibilities. I would therefore treat any figure in Gravy as one part of a wider comparison, not as a direct statement that buying is automatically cheaper or better.
The app’s audience focus is a genuine strength here. A general investment or budgeting app may show excellent charts but leave a first-time buyer wondering what to do next. Gravy keeps attention on the transition from renting to owning. That focus can reduce the temptation to optimize unrelated financial metrics while ignoring the practical steps that make a purchase possible.
Still, faster does not mean careless. I would never use a shortcut that skips reading a definition or accepting a suggested assumption without checking it. Homebuying language often sounds familiar while hiding important distinctions. If the app points me toward a concept I do not understand, I would pause and verify it through a lender, housing counselor, or another reliable source before making a commitment.
Where the app reaches its limits
The biggest limitation is built into the subject: an app cannot know the full reality of my future purchase. It cannot replace a lender’s assessment, a professional inspection, legal advice, or a close reading of loan documents. Even a well-organized plan can become outdated when rates, local costs, employment, or personal circumstances change. I see Gravy as a preparation layer, not the final authority.
It may also be the wrong choice for someone who already has a detailed homebuying system. If I track every account in a spreadsheet, speak regularly with a housing professional, and already have a clear savings schedule, a focused app may add another place to maintain. The extra convenience is worthwhile only if it makes the process easier, not if it creates duplicate data entry.
Users looking for advanced investment analysis or complete banking management should set expectations accordingly. A homebuying-focused tool is not the same as a portfolio platform, a bank dashboard, or a full household accounting package. I would choose a different app for those jobs and keep Gravy for the specific question of preparing to buy.
The presence of in-app purchases is another point to consider. The app itself is free, but individual purchases can cost from $4.99 to $59.99. I would review what a purchase provides before paying and ask whether it changes my decision-making or merely adds convenience. A paid feature is easier to justify when it replaces work I would otherwise struggle to do; it is harder to justify when the same result can be reached with a simple note, calculator, or conversation with a professional.
The public response is encouraging but still relatively modest in scale: Gravy holds a 4.5 average from around 387 ratings, with over 10K installs and 49 written reviews. I read that as a sign of a focused app with a real audience, not as proof that it will fit every financial situation. A smaller user base can also mean that I should be especially attentive to how well the current version works on my device and whether its approach matches my needs.
Age suitability is broad, with an Everyone content rating, but financial maturity is a different matter. A younger renter may find the planning language accessible, yet buying a home involves obligations that should be discussed with trusted adults or qualified professionals. The rating describes general content suitability; it does not turn the app into personalized financial advice.
Who will get the most from Gravy?
I would recommend it most to a renter who is serious enough to plan but not yet confident about the process. That person may have a vague goal, scattered notes, and several unanswered questions. Gravy can provide a homebuying-centered place to turn that uncertainty into a sequence of manageable checks.
It is also a good fit for someone who benefits from visible progress. Saving for a deposit can feel unrewarding when the goal is far away. A repeatable review makes the effort easier to connect with a future decision, especially when I use it alongside automatic saving and a broader monthly budget.
I would be more cautious recommending it to a buyer who is already at the offer stage, has complex self-employment income, owns multiple properties, or needs detailed comparisons between loan products. Those situations call for professional guidance and more specialized tools. Gravy may still help organize the personal goal, but it should not be the central decision system.
My verdict after using it as a planning companion
Gravy: Homebuying for renters works best when I use it to build habits, not to outsource judgment. Its homebuyer focus gives renters a clearer starting point than a generic finance app, and its free entry makes it easy to test without committing money immediately. The strongest experience comes from combining it with accurate numbers, regular reviews, and a separate method for checking the full household budget.
I would install it if I were renting, hoping to buy, and unsure how to turn that hope into a repeatable plan. I would keep my expectations measured, check every assumption, and treat optional purchases carefully. If I already had a mature financial workflow or needed deep mortgage and investment analysis, I would choose more specialized alternatives instead.
After a few consistent check-ins, the real benefit is not a single answer about whether I can buy. It is a clearer view of what needs to happen before that decision becomes responsible. That makes Gravy a useful companion for first-time buyers who want structure, as long as they remember that the final homebuying decision belongs to them and the professionals helping them.
Frequently Asked Questions
What is Gravy: Homebuying for Renters?
Gravy is a homebuying-focused app designed to help renters explore the path toward purchasing a home. It provides guidance, educational resources, and tools intended to make the buying process easier to understand, from preparing financially to considering available homebuying opportunities. It is best viewed as a planning and support platform rather than a replacement for a lender, real estate agent, or legal professional.
How can Gravy help renters prepare to buy a home?
The app can help renters organize their homebuying journey by learning about affordability, budgeting, savings, credit readiness, and the general steps involved in purchasing property. Its content is useful for people who are not sure where to begin or who want a clearer plan before contacting professionals. However, users should verify rates, eligibility requirements, and financial details because personal circumstances and program availability can vary.
Does Gravy provide money or financial assistance for a home purchase?
Gravy may present homebuying support, resources, or opportunities that could be relevant to eligible renters, but users should not assume that every person will qualify for financial assistance. Availability, terms, geographic coverage, income requirements, and other conditions may apply. Before relying on any offer, carefully review the current terms in the app and consult a qualified mortgage or financial professional.
Is Gravy suitable for first-time homebuyers?
Yes, Gravy is particularly relevant to renters who are considering buying their first home and need help understanding the process. The app can make unfamiliar topics feel more approachable and may help users identify practical next steps. Still, first-time buyers should compare multiple lenders, understand closing costs and ongoing ownership expenses, and obtain independent advice before making a major financial commitment.
Is Gravy free to download and use?
The app may be available to download without an upfront charge, but users should check its current App Store or Google Play listing for accurate information about pricing, optional services, subscriptions, or fees. Some features, consultations, or homebuying programs may have separate eligibility rules or costs. Review the privacy policy and terms of service as well, especially before submitting financial or personal information.


